Starting college is exciting—but financially, it can feel confusing. If you’ve never had a credit card before, you’re probably wondering where to even begin. The good news? There are best credit cards for college students USA specifically designed for beginners with no credit history.
This guide is built for students just like you. We’ll break down the best beginner-friendly cards, what to look for, how to apply, and how to build your credit the right way. By the end, you’ll know exactly which card fits your situation—and how to use it smartly. TABLE OF CONTENTS
- Can you get a credit card in college with no credit history?
- What to look for in a student credit card
- Best credit cards for college students USA 2025 — our top picks
- Comparison table: student credit cards at a glance
- How to apply for a student credit card (step-by-step)
- How to use your first credit card responsibly
- How long does it take to build credit as a student?
- Frequently asked questions
Can you get a credit card with no credit history as a college student?
Yes—you absolutely can.
There are credit cards made specifically for students who have no credit history at all. Traditional credit cards usually require a credit score because banks want proof you can repay what you borrow. As a student, you simply haven’t had the chance to build that history yet.
That’s where beginner cards come in. You have two main options:
- Student credit cards — designed for college students with little or no credit
- Secured credit cards — require a refundable deposit but are easier to get approved for
One important rule: under the CARD Act of 2009, if you’re under 21, you’ll need either:
- Proof of income (part-time job, allowance, financial aid refunds), or
- A co-signer
The upside? Once you get approved and use your card responsibly, it becomes one of the fastest ways to build your credit score from scratch.
What to look for in your first student credit card
Before choosing a card, understand what actually matters.
Annual fee
The best student cards charge $0 annual fee. You shouldn’t pay just to build credit. Secured cards sometimes charge a fee—but they can still be worth it if approval is guaranteed.
APR (interest rate)
Most student cards have 20%–30% APR. But here’s the key: 👉 If you pay your full balance every month, you pay zero interest.
Credit limit
Expect a starting limit between $300–$1,000. Keep usage below 30% of your limit to build your score faster (learn more about credit utilization ratio).
Rewards (cashback / points)
Some cards offer:
- 1%–5% cashback
- Rewards on dining, groceries, or online shopping
Nice bonus—but don’t prioritize rewards over approval odds.
Credit-building tools
Look for:
- Reporting to Experian, Equifax, and TransUnion
- Free credit score tracking
- Automatic credit limit increases after good payment history
Best credit cards for college students USA 2025 — our top picks
We selected these cards based on:
- No annual fee
- Approval with no credit history
- Reports to all 3 bureaus
- Student-friendly features
Some links may be affiliate links. We may earn a commission if you apply—this doesn’t affect our rankings.
Discover it Student Cash Back — best for cashback rewards
Perfect for students who want real rewards while building credit.
Key details:
- Annual fee: $0
- APR: 18.24%–27.24%
- Rewards: 5% rotating categories, 1% everything else
- Credit score required: None
- Reports to all 3 bureaus: Yes
- Credit limit: Starts around $500
Why we like it: You earn 5% cashback in rotating categories like Amazon, gas, and restaurants. Plus, Discover matches all cashback in your first year.
Watch out for: You must activate categories every quarter.
Capital One SavorOne Student Cash Rewards — best for dining & entertainment
Great for students who spend on food, streaming, and fun.
Key details:
- Annual fee: $0
- APR: 19.99%–29.99%
- Rewards: 3% dining, entertainment, groceries
- Credit score required: None
- Reports to all 3 bureaus: Yes
Why we like it: No rotating categories—simple, consistent rewards.
Watch out for: Higher APR if you carry a balance.
Bank of America Customized Cash Rewards for Students — best for flexible rewards
Ideal if you want control over where you earn cashback.
Key details:
- Annual fee: $0
- APR: 19.24%–29.24%
- Rewards: 3% in chosen category
- Credit score required: None
Why we like it: Choose your top category (online shopping, gas, dining, etc.).
Watch out for: Cashback is capped quarterly.
Discover it Secured Credit Card — best for guaranteed approval
Best fallback if you’re denied other cards.
Key details:
- Annual fee: $0
- APR: 28.24%
- Rewards: 2% dining/gas
- Credit score required: None
- Security deposit: $200+
Why we like it: Earn cashback while building credit—rare for secured cards. Upgrade possible after 7 months.
Watch out for: Requires upfront deposit.
Chase Freedom Student Credit Card — best for future upgrades
Good entry into the Chase ecosystem.
Key details:
- Annual fee: $0
- APR: 19.99%–28.74%
- Rewards: 1% flat cashback
Why we like it: Credit limit increase after 5 on-time payments.
Watch out for: Lower rewards than competitors.
Petal 2 “Cash Back, No Fees” Visa — best for international students
Great if you don’t have an SSN.
Key details:
- Annual fee: $0
- APR: 18.24%–32.24%
- Rewards: 1–1.5% cashback
- Credit score required: None (uses bank history)
Why we like it: Accepts ITIN and evaluates income patterns.
Watch out for: Starts with lower rewards initially.
Student credit cards compared at a glance
APRs are variable—check issuer sites before applying.
How to apply for a student credit card in the USA — step by step
Step 1 — Choose the right card
- Have income → go for a student card
- No income → secured card or co-signer
Step 2 — Gather documents
- SSN or ITIN
- Date of birth (18+)
- US address
- Income info
- School details
Step 3 — Apply online
- Takes ~5 minutes
- Instant decision in most cases
- Card arrives in 7–10 days
Step 4 — Set up autopay immediately
Set autopay for full balance—this alone protects your credit score.
5 rules for using your student credit card the right way
- Pay full balance monthly — avoid interest
- Stay under 30% utilization — boosts score
- Never miss payments — biggest factor in credit score
- Don’t apply for multiple cards — avoid score drops
- Track your credit score monthly — catch issues early
How long does it take to build a credit score from scratch?
- 3–6 months: first credit score appears
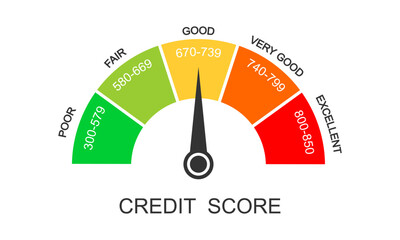
- 12–18 months: reach ~680–700 with good habits
Speed it up by:
- Paying on time
- Keeping low balances
- Becoming an authorized user
Use tools like Experian or Credit Karma to track progress. Conclusion
If you’re starting from zero, the Discover it Student Cash Back is the best overall choice for most students. If approval is your concern, go with the Discover it Secured.
The key isn’t just getting a card—it’s using it right. Pay your balance in full, stay consistent, and you’ll build strong credit faster than you think.
Ready to start? Check the comparison table above and pick the card that fits your situation.
Frequently Asked Questions
Written by
Harshal Chaklasiya
Editorial contributor at Blynter. Passionate about personal finance, investing, budgeting, and creating practical money guides that help readers make smarter financial decisions.